RytNow connects your bank with its partner showrooms. Dealers submit car finance applications on the spot, your credit policy decides in real time, and approved deals move straight to settlement.
The customer, the showroom and the bank, in one flow.
Every application is one shared session. Each side sees it in its own portal, with the same data and the same status.
Customer
Apply from the showroom or the app
The customer applies through the dealer, or on their own in your white-label app.
Pick the showroom, car category and price
Scan the national ID instead of filling forms
See matching down-payment plans and the monthly installment
Track the application status
Showroom
Close the deal while the customer is there
Dealers and sales agents work in the dealer portal, on the web or on mobile.
Create a new application in one guided session
Get the eligibility result and decline reasons instantly
Track every application from start to finance created
Receive settlements on a fixed cycle
Bank
Decide with your own rules
Your teams run the product from the RytNow Finance admin portal.
Set credit policy, decision tables and iScore rules without code
Price by campaign, offer, merchant or branch
Review credit applications with full iScore detail
Approve dealer settlements and follow collections
At the showroomThe decision comes before the customer leaves the showroom.Eligibility runs in real time, and decline reasons show on the dealer's screen.Dealer portal on the sales floor, web and mobile
The journey
Seven steps. One session.
The same guided journey runs in the dealer portal and the customer app. An unfinished session can be resumed with the customer's phone number.
Your bank configures which steps run and which checks each step calls, in the application workflow designer.
Verify the phone number
A one-time code confirms the customer and opens the application session.
Choose the finance scheme
Auto finance on a down-payment basis.
Vehicle and financing
Showroom, branch, car category and price. The customer sees the down-payment plans, the tenor range and the monthly installment.
Down-payment tiersTenor sliderLive installment
Scan the national ID
Smart OCR reads the Egyptian national ID, front and back. The customer confirms the data and adds income and address.
OCRManual fallback
Check eligibility
Your credit policy runs in real time: iScore, debt burden and policy checks. The result is the maximum financing and the plans this customer can take.
Real-time iScoreDebt burdenPolicy checks
Vehicle details and documents
Brand, model, year and chassis number, plus the car quotation or proforma invoice and the Murabaha request form.
Review and submit
The finance is created on submit, or the dealer gets clear decline reasons on the same screen.
After submission, in the bank's credit applications
PendingApprovedFundedDealer settled
Credit decision
Your credit policy, applied in real time.
Every rule is a configured value in the admin portal, so your risk team changes it without a code release.
Credit policyPre-screening and customer selection criteria, tenor limits and the default offer.
Decision tablesMaximum financing and down-payment limits by car category.
iScore rulesHow each bureau facility counts toward debt burden and scoring.
PricingRate, admin fees and rebate by campaign, offer, merchant or branch.
Branch catalogueInclude or exclude vehicle categories per showroom branch.
Income assessmentDeclared, down-payment-derived and iScore-derived income, compared side by side.
Every decline has a reason
When an application does not pass, the dealer sees why on the same screen, so the customer can adjust the plan or the down payment.
Age outside policy
Income below minimum
Debt burden above limit
No credit bureau record
Bureau decline
Nationality not eligible
Area not covered
Below minimum financed amount
Eligible customers see the plans they qualify for and the maximum financing.
For showrooms
A dealer portal built for the sales floor.
DashboardDeals, approvals and monthly volume at a glance.
New applicationThe guided seven-step journey, with ID scanning and an instant eligibility check.
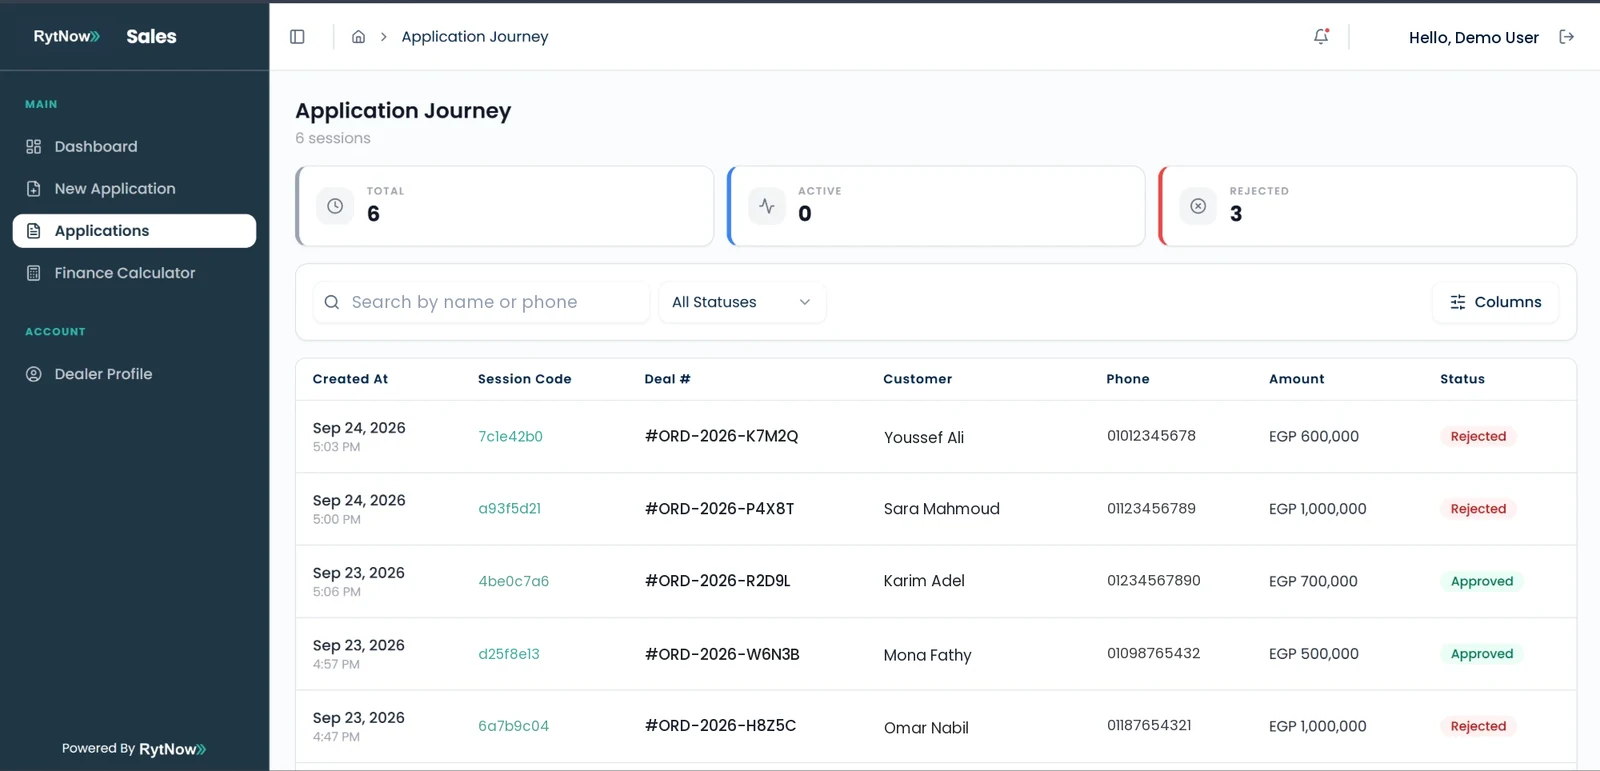
ApplicationsEvery application session and its status, and resume any open one by phone number.
ActiveLoan CreatedRejectedExpiredAbandoned
Finance calculatorQuote the installment, total cost and interest before the customer applies.
Web and mobileThe same portal on the desktop and as a mobile app for sales agents.
Settlement
Dealers get paid on a set cycle.
Authorized orders are grouped into settlements per merchant. Each one goes through an approval queue, and reversals have their own approval flow.
Total financedEGP 450,000
−
Merchant rebateEGP 9,000
=
Transfer to dealerEGP 441,000
Illustrative figures. Rebate type, value and settlement cycle are set per merchant.
PendingApprovedProcessingSettled
Car finance assistant
Apply by talking, in Arabic or English.
An AI assistant in the customer app walks the applicant through the same journey by chat or voice: budget, showroom, plan, ID photos, credit check and pre-approval. Then it hands the case to your sales team.
Figures come from your pricingThe assistant never quotes a rate or installment on its own. Every number is calculated from your configured terms.
Same checks, same policyIt runs the same OCR, iScore and eligibility steps as the dealer portal.
Car finance assistantChat or voice
Hi, I can help you finance a car. What is your budget, and which showroom are you buying from?
Thanks. With a 40% down payment over 48 months, here is your plan:
Monthly installment EGP 13,500Pre-approved
I have passed your request to the showroom's sales team. They will contact you within one working day.
Questions
For banks and showrooms
Who makes the credit decision?
The bank. RytNow runs your credit policy, decision tables and iScore rules automatically, and your team reviews the credit applications in the admin portal.
Can we use our own rates and fees?
Yes. Rate, admin fees and rebate are configured by campaign, offer template, merchant or branch, and the installment shown everywhere is calculated from them.
How do showrooms join?
The bank adds each merchant and its branches in the admin portal. Dealers and sales agents then sign in to the dealer portal on the web or the mobile app.
What does the customer need?
Their national ID, income and address details, a car quotation or proforma invoice, and the Murabaha request form.
How are dealers paid?
Authorized orders are grouped into settlements per merchant: the financed amount minus the merchant rebate, transferred on the settlement cycle you set.
Does it work with Murabaha car finance?
Yes. The journey collects the Murabaha request form, and the post-approval checklist includes the Murabaha sale agreement.
See auto finance running on your products.
We will walk you through the dealer journey, the credit decision and settlement, set up with your own terms.